What is SIF? Specialised Investment Fund Simply Explained
What is SIF? Specialised Investment Fund Simply Explained
By Midas Finserve/ARN - 113074 | Last updated: 06/10/2026 |
Key Highlights
• What it is: A SIF (Specialised Investment Fund) is a SEBI-regulated investment category offered by mutual fund houses (AMCs), effective from 1 April 2025.
• Minimum investment: ₹10 lakh per PAN across all SIF strategies of one AMC. Accredited investors are exempt.
• Key difference: SIFs can take long and short positions through derivatives, with unhedged short exposure capped at 25% of net assets.
• Where it fits: It sits between mutual funds (SIP from ₹100) and PMS (₹50 lakh minimum).
• Main cautions: SIFs have no long-term track record yet, and liquidity and fees vary by strategy.
SIF is a new SEBI-regulated category that gives investors access to strategies mutual funds can't use. It was designed for people who have ₹10 lakh or more to invest and want flexibility, but are not ready for PMS's ₹50 lakh entry point.
The difference from a mutual fund goes beyond the minimum amount. What matters is what the structure allows: derivatives, short positions and, in some strategies, performance-linked fees. These features widen the range of possible returns, and also the range of possible losses.
What is a Specialised Investment Fund (SIF)?
A SIF (Specialised Investment Fund) is a SEBI-regulated, unit-based investment product from an AMC. It needs a minimum of ₹10 lakh per PAN per AMC. It allows strategies that regular mutual funds cannot use, such as long-short equity with unhedged short exposure of up to 25% of net assets.
You hold units and track a NAV, just as in a mutual fund, while a fund manager runs the strategy. SEBI announced the framework in February 2025, and it took effect on 1 April 2025. You may see it spelled "Specialized" too.
The simple way to see it is: Mutual Funds → SIF → PMS → AIF. A SIF is not a "better mutual fund". It is a separate category with its own risk, reward and rules.
Where does SIF fit among investment options?
SIF fills the gap between mutual funds and PMS. Before it existed, an investor with ₹10 lakh to ₹50 lakh had few regulated options beyond conventional mutual funds.
• Mutual funds: start from ₹100 through a SIP, with defined categories.
• SIF: ₹10 lakh minimum, with derivatives and long-short strategies.
• PMS: ₹50 lakh minimum, with customised portfolios.
• AIFs: ₹1 crore minimum, with complex structures for sophisticated investors.
How does a SIF work?
You invest in a SIF strategy and receive units. The fund manager pools investor money and buys and sells securities as per the strategy's rules. You track the NAV and redeem as the scheme allows.
The main difference from a regular mutual fund is that a SIF can take both long and short positions using derivatives.
What are long and short positions in a SIF?
A long position means buying a security and profiting if its price rises. A short position means selling a security you don't own, hoping to buy it back at a lower price.
• Long: price goes up → you make money 📈
• Short: price goes down → you make money 📉
A SIF manager can go long on one stock or sector and short another at the same time. This can help in uncertain markets, but a wrong short call can multiply losses. Long-short funds can also underperform when markets move against them.
What is the minimum investment in a SIF?
The minimum investment is ₹10 lakh per investor at PAN level, across all SIF strategies of a single AMC. It is not per scheme. For example, ₹6 lakh in one strategy plus ₹4 lakh in another from the same AMC meets the requirement. Accredited investors are exempt.
Mutual funds let you start with a few hundred rupees, so a SIF needs far more capital. SIPs, SWPs and STPs are possible in a SIF, as long as the ₹10 lakh minimum is maintained. Having ₹10 lakh does not make a SIF right for you. Check your risk appetite, time horizon and existing portfolio first.
What are the different SIF strategies?
SEBI allows several strategy types, each with its own asset mix and short-exposure limits:
• Equity Long-Short: at least 80% in equity, with up to 25% unhedged short exposure through derivatives.
• Equity Ex-Top-100 Long-Short: at least 65% in equities outside the top 100 companies by market cap, with up to 25% short exposure.
• Sector Rotation Long-Short: at least 80% in equity across a limited number of sectors, with short exposure capped at 25%.
• Debt Long-Short: debt-focused strategies that can use exchange-traded debt derivatives for short exposure, with sector limits.
• Hybrid Long-Short: at least 25% in equity and at least 25% in debt, with up to 25% short exposure.
• Active Asset Allocation: shifts money across asset classes based on market views, with short exposure up to 25%.
The risk differs from one strategy to the next, so read the scheme's information document before investing.
More flexibility usually comes with more risk and cost, so a SIF is not automatically better than a mutual fund. Read more about mutual fund investment and Portfolio Management Services to compare.
What are the benefits of a SIF?
A SIF gives access to strategies regular mutual funds can't offer. The main benefits are:
• Flexible strategies: long-short, sector rotation and active asset allocation.
• Professional management within a regulated, unit-based structure.
• Hedging ability that can help manage volatility.
• Lower entry than PMS: ₹10 lakh versus ₹50 lakh.
• Simpler tax treatment than PMS: you are taxed at redemption, not on every trade inside the fund.
What are the risks of investing in a SIF?
Yes, a SIF carries more risk than most mutual funds. The key risks are:
• Derivative and short-position risk: a wrong call on a short position or a derivative can amplify losses in ways a buy-and-hold fund cannot.
• Liquidity risk: some SIF strategies may not allow daily redemption. Exit may be possible only in defined windows, so check the scheme document before investing.
• Limited track record: SIFs began only in 2025, so there is no 5- or 10-year history to judge them by.
• Fee risk: some strategies may charge performance-linked fees. Total cost can be noticeably higher in a good year than in a flat-fee mutual fund.
• Minimum-holding rule: if your holding drops below ₹10 lakh because of your own redemptions, you may have to exit fully. Check the scheme document for how market-driven dips are handled.
Before investing, check the Risk-o-Meter, asset allocation, derivative use, liquidity terms and fees. You can also take our risk profile test to understand your risk appetite.
How is a SIF taxed?
SIFs follow mutual fund-style taxation. Tax is levied on you at redemption, and the rate depends on the fund's asset mix and your holding period. This is simpler than PMS, where gains are taxed on each transaction. Tax rules change, so confirm current rates with a tax professional before investing.
Who should invest in a SIF?
SIFs suit experienced investors who understand derivatives and short positions and have ₹10 lakh or more of surplus money beyond emergency and near-term needs. They are not for beginners, or for money you may need soon.
Ask what a SIF will do for your portfolio over the long run, not which scheme returned the most. A SIF should fit your goals and risk profile, not tempt you with the chance of quick gains.
How to invest in a SIF
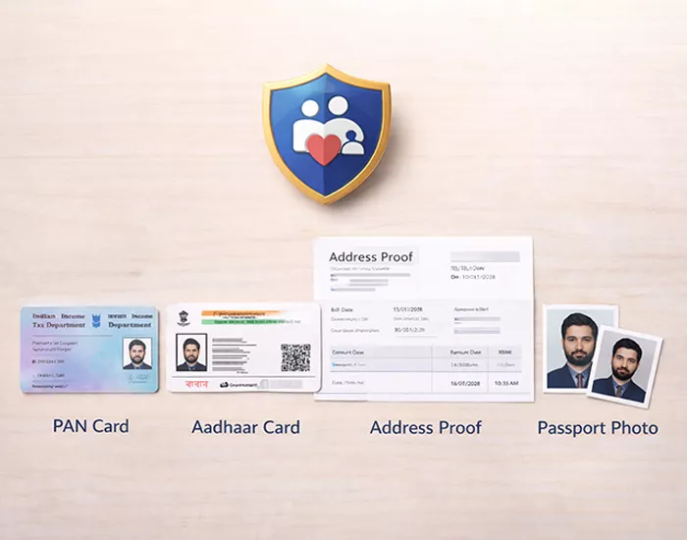
1. Check eligibility: keep at least ₹10 lakh available, unless you are an accredited investor.
2. Complete KYC if you haven't already.
3. Choose an AMC and strategy that fits your goals and risk profile.
4. Read the Investment Strategy Information Document (ISID).
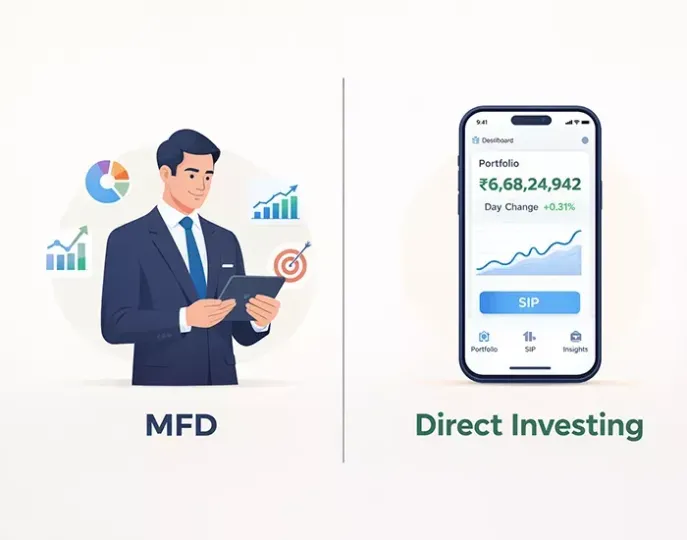
5. Invest through a registered distributor or directly with the AMC.
Key Takeaways
• SIF is a SEBI-regulated category effective April 2025, with a ₹10 lakh minimum per PAN per AMC.
• It allows long-short strategies and derivatives, which mutual funds do not.
• Unhedged short exposure is capped at 25%, which creates risks mutual funds don't have.
• The category has no long-term track record yet.
• Liquidity and fees vary by strategy, so read the scheme documents before investing.
SIF vs Mutual Fund vs PMS vs AIF: what's the difference?
A SIF offers more strategy flexibility than a mutual fund, and a lower entry point than PMS or an AIF. Here is the comparison:
|
Factor |
Mutual Funds |
SIF |
PMS |
AIF |
|---|---|---|---|---|
|
Minimum investment |
No minimum (SIP from ₹100) |
₹10 lakh (PAN level, per AMC) |
₹50 lakh |
₹1 crore |
|
Strategy flexibility |
Defined categories |
Advanced: derivatives, long-short |
High: customisable |
High: complex structures |
|
Short selling |
Hedging only, no unhedged shorts |
Up to 25% of net assets |
Permitted |
Permitted, as per category |
|
Taxation |
At redemption |
At redemption (similar to MFs) |
At transaction level |
Depends on category |
|
Fees |
Expense ratio |
Expense ratio; some strategies may add performance-linked fees |
Management + performance fee |
Management + performance fee |
|
Transparency |
Daily NAV |
NAV-based |
Periodic reporting |
Periodic reporting |
|
Track record |
Long history |
Introduced 2025: limited data |
Varies by manager |
Varies by manager |
More flexibility usually comes with more risk and cost, so a SIF is not automatically better than a mutual fund. Read more about mutual fund investment and Portfolio Management Services to compare.
Frequently Asked Questions (FAQs)
1. What is the full form of SIF?
SIF stands for Specialised Investment Fund, a SEBI-regulated category that sits between mutual funds and PMS.
2. What is the minimum investment in a SIF?
₹10 lakh per investor at PAN level, across all SIF strategies of one AMC. Accredited investors are exempt.
3. Is a SIF safe?
No investment is risk-free. SIFs are regulated by SEBI, but they use derivatives and short positions, so they carry higher risk than most mutual funds.
4. What is the difference between SIF and a mutual fund?
A SIF can take long and short positions through derivatives, but needs ₹10 lakh to start. Mutual funds have defined categories and let you invest with much smaller amounts.
5. What is the difference between SIF and PMS?
A SIF is a pooled, NAV-based product starting at ₹10 lakh. PMS needs ₹50 lakh, is customised, and is taxed on each transaction.
6. How is a SIF taxed?
Similar to mutual funds: you pay tax at redemption, based on the fund's asset mix and holding period.
7. Can I invest in a SIF through SIP?
Yes. SIPs, SWPs and STPs are allowed, provided the ₹10 lakh minimum is maintained.
8. Can an existing mutual fund investor invest in a SIF?
Yes, if they meet the ₹10 lakh minimum and have completed KYC. Whether it suits them depends on their risk profile and goals.
9. Does a SIF offer daily liquidity?
Not always. Some strategies may allow redemption only at set intervals, so check the strategy's information document before investing.
10. Is a SIF better than a mutual fund?
Not necessarily. It offers more flexibility, but with higher risk, cost and a higher entry amount. It suits experienced investors.
Final thoughts
SIFs bring long-short and flexible strategies to investors who want more than a mutual fund offers but are not ready for PMS. More flexibility also means more responsibility, so understand the strategy, liquidity terms and costs first. For the official rules, see the SEBI SIF circular.
Want help deciding if a SIF fits your portfolio? Speak to our advisors.
Want a quicker walkthrough? Watch our video on Specialised Investment Funds for a simple, step-by-step explanation - https://www.youtube.com/watch?v=4KfwuO4Ylmg&t=22s
Disclaimer: This article is for educational purposes only and is not investment advice or a recommendation. Investments in a Specialised Investment Fund involve relatively higher risk, including potential loss of capital, liquidity risk and market volatility. Please read all scheme-related documents carefully and consult a qualified financial advisor before investing. Mutual fund investments are subject to market risks.